Opening a bank account in the UAE used to mean a branch visit, a stack of papers, and a long wait. Today, many residents do it from a phone in a few minutes. Digital banking UAE has grown from a convenience into the everyday way people get paid, save, send money, and run small businesses. This guide explains how it works, who offers it, what it costs, and how to choose the right account.
What Is Digital Banking, and How Is It Different From Online Banking?
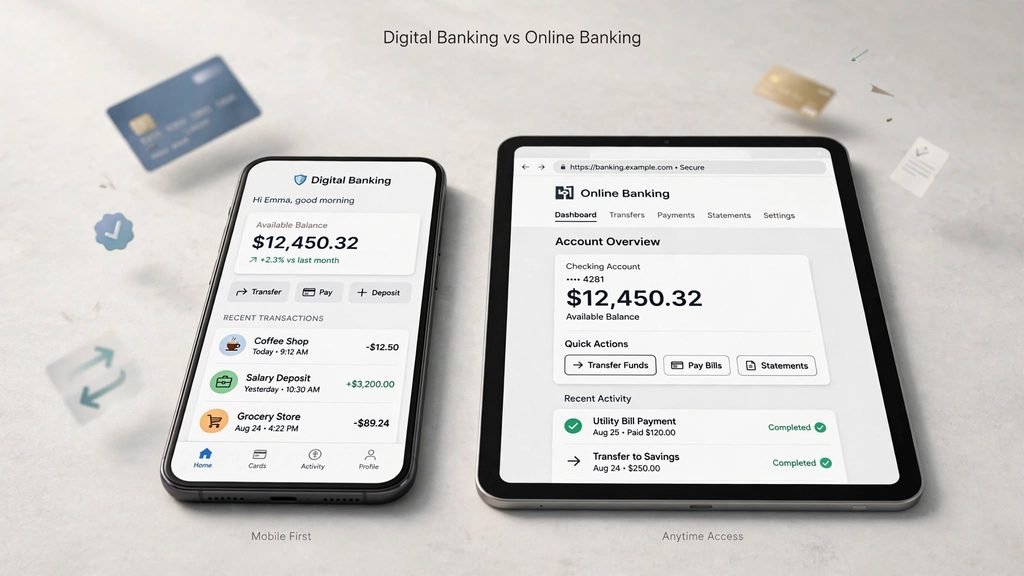
Digital banking and online banking sound like the same thing, but they are not.
Online banking UAE usually means a traditional bank that lets you check balances, pay bills, and move money through a website or app. The bank still has branches, and the app is an add-on to the existing service.
Digital banking means the whole bank is built around the app. You open the account, get your card, contact support, and manage savings without visiting a branch. Some digital banks have no branches at all. Others are digital brands run by a traditional bank.
Why the UAE Leads in Digital Finance
Three things push the UAE ahead of many countries.
- Regulation: The Central Bank of the UAE (CBUAE) has created clear paths for digital banks, wallets, and open finance.
- Adoption: Most residents already use smartphones for shopping, transport, and government services, so banking on a phone feels natural.
- Infrastructure: Fast payment rails, digital identity through Emirates ID, and strong mobile networks make instant onboarding possible.
A Quick Look at the 2026 Landscape
Three names define the current picture. Aani, the instant payment platform, has reached about 12.5 million users. Open Finance is letting banks and approved providers share customer data with consent. Neobanks like Wio and Zand now compete directly with older banks. Together they have made digital banking UAE faster, cheaper, and easier to compare.
Regulatory Framework and Licensing
The Role of the Central Bank of the UAE
CBUAE licenses and supervises banks, finance companies, exchange houses, and payment providers. It also sets rules on anti-money laundering, customer identification, capital, and consumer treatment. When you use a licensed provider, it must follow these rules.
Digital Bank Licence vs Stored Value Licence
This difference matters more than most people realise.
A digital bank licence lets a company operate as a full bank. It can hold deposits, offer savings accounts, and lend money.
A stored value facility (SVF) licence covers wallets and prepaid products. A wallet lets you load money, spend it, and send it, but it is not a bank account. It usually cannot offer loans or the same range of savings products.
Open Finance and Instant Payments
The Open Finance framework lets you share your financial data with approved providers, such as a budgeting app or a lender, without handing over your password. It is meant to create better comparisons and more personal services.
Aani runs on the same push toward speed. Transfers between participating banks and apps can land in about three seconds, and you can pay using a mobile number or an alias instead of long account details.
Compliance for Individuals and Businesses
Individuals need a valid Emirates ID and go through KYC (know your customer) checks. Businesses need a trade licence, ownership details, and proof of activity. Expect extra questions if your income or transactions look unusual. That is normal and part of anti-money laundering rules.
Types of Digital Banking Providers in the UAE
Standalone Digital Banks
Wio and Zand are built as digital banks from the start. They have no legacy systems, so their apps tend to feel quick and simple.
Digital Arms of Traditional Banks
Mashreq Neo, Liv by Emirates NBD, and ADIB Hayyak are digital brands from established banks. You get a modern app backed by a larger institution.
Fintech Wallets and Remittance Apps
e&Money, Pyypl, and Wise focus on payments, wallets, and sending money abroad. They are useful, but they play a different role from a bank.
Bank vs Wallet vs Remittance Provider
| Type | What it does best | Main limit |
|---|---|---|
| Bank | Deposits, salary, savings, loans | Needs full onboarding |
| Wallet | Everyday spending and top-ups | Fewer banking products |
| Remittance provider | Sending money abroad | Not built for daily banking |
Core Features of Digital Banking in the UAE
Account Opening
You usually need your Emirates ID, a selfie or video check, and your phone. Many providers finish onboarding within minutes, though final approval can take longer if extra checks are needed.
Salary Deposits and Zero-Balance Accounts
Many digital banks let you receive your salary with no minimum balance. That is a big change from traditional accounts, which often demand a set balance to avoid penalties.
Transfers
You can send money three main ways. UAEFTS handles local transfers between banks. SWIFT handles international transfers. Aani handles instant payments inside the UAE.
Savings, Budgeting, and Multi-Currency Tools
Most apps let you split money into savings pots, track spending by category, and hold more than one currency. Wio’s savings spaces and similar tools help you set goals without opening extra accounts.
Cards
You can get a virtual card instantly, and many banks send a physical card later. Both work for online shopping and international payments, and virtual cards add safety when you shop on new websites.
Security
Apps use fingerprint or face login, encryption, device binding, and live fraud monitoring. If something looks odd, the bank can freeze the card from the app in seconds.
Top Digital Banks in the UAE (2026)
Wio Personal and Wio Business
Wio is a strong pick for freelancers and small businesses because one app covers personal and business needs. It offers savings spaces, multi-currency support, and quick onboarding.
Mashreq Neo and NeoBiz
Mashreq Neo suits salaried users who want a simple account with a big-bank backing. NeoBiz serves SMEs that want fast company account setup and basic business tools.
Liv by Emirates NBD
Liv is aimed at younger users. It offers a zero-balance account, a playful app, and lifestyle perks. It works well if you like an app that feels more social than formal.
Zand
Zand is known for its focus on corporate clients, wealth services, and digital assets. It suits users who want more than everyday banking.
ruya
ruya is a Sharia-compliant digital bank. It is a good fit if you want Islamic banking principles in a modern app.
Mbank
Mbank is a newer zero-balance digital bank. Because newer providers change their terms often, check the latest features and fees before you apply.
Digital Banking for Individuals
Salary Accounts and Minimum Balances
Most digital banks accept salary transfers without a minimum balance. Traditional banks commonly require AED 3,000 or more, and they charge a monthly penalty if you fall below it. The exact numbers differ by bank, so read the fee sheet.
Savings Rates
Wio, Mashreq Neo, and ruya all offer savings options. Rates move often and may depend on conditions such as salary transfer or minimum activity. Check the current rate inside the app before you decide.
Everyday Spending, Bills, and Budgeting
You can pay utility bills, mobile top-ups, and government fees from most apps. Spending trackers group purchases by category, which helps you see where your money goes each month.
Travel and Multi-Currency Features
Some apps let you hold or convert foreign currency at fair exchange rates. This helps when you travel often or send money to family in another country.
Eligibility for Expats, Tourists, and Non-Residents
UAE residents with a valid Emirates ID can open most digital accounts. Tourists and non-residents usually cannot, because the KYC process depends on Emirates ID. Tourists often use prepaid cards or wallets instead. Non-residents should ask the provider directly about their options.
Digital Banking for Businesses and Freelancers
Business Account Onboarding
LLCs, free zone companies, and freelancers can all apply, but the paperwork differs. LLCs need a trade licence and ownership documents. Free zone companies need their free zone licence. Freelancers may need a freelance permit. Digital banks usually take less time than traditional banks to open these accounts.
Multi-User Access and Accounting Tools
Many business apps let you add team members with different permission levels. Some connect with Xero, Zoho, and QuickBooks, which saves hours on bookkeeping.
Payments, POS, and Payroll
You can send invoices, collect card payments, and pay staff from one platform. Some providers offer POS devices and salary payment tools built into the same app.
Best Options for SMEs
Wio Business, NeoBiz, Zand, and E20 are the main names to compare. Wio Business fits freelancers and small firms, NeoBiz suits Mashreq-linked SMEs, Zand suits larger or more complex needs, and E20 suits companies already close to Emirates NBD. For more on this topic, explore our guide to business banking UAE.
Fees, Charges, and Hidden Costs
Zero-balance does not mean zero cost. Watch for these:
- Monthly fees and penalties: Some accounts charge a fee if your balance or salary activity drops.
- Transfer fees: Local transfers are often cheap or free. International SWIFT transfers can cost AED 50 or more, plus intermediary bank charges.
- Card fees: Replacement cards and some premium cards carry annual charges.
- FX conversion: Banks add a margin on foreign currency spending. A small percentage adds up fast on large purchases.
- ATM usage: Withdrawals at other banks’ ATMs may cost a few dirhams each time.
- Savings conditions: Higher rates often need a salary transfer or a spending target.
Always open the fee schedule before you sign up. It is the most honest part of any bank’s website.
Safety, Security, and Consumer Protection
CBUAE Regulation
Licensed banks and payment providers must follow CBUAE rules on capital, customer identification, and complaint handling. Always confirm that a provider is licensed before you trust it with money.
App Security
Biometric login, encryption, and instant card freezing protect your account. Turn on every security option your app offers.
Scam Awareness and Safe Habits
Most losses come from tricked customers, not broken systems. Follow these habits:
- Never share your OTP, PIN, or card details with anyone, including someone who says they are from the bank.
- Ignore links in unexpected SMS or WhatsApp messages.
- Use the official app only, and keep it updated.
- Check the recipient’s name before you confirm a transfer.
- Report suspicious activity to your bank right away.
Digital Banking Trends Shaping the UAE
Instant payments. Aani is making fast transfers the default, and paying by mobile number is becoming normal.
Open Finance. Apps can pull data from several banks into one view, which makes budgeting and loan comparison easier. Read more about this shift in our coverage of fintech in the UAE.
AI money tools. Banks are adding smart spending insights, chat support, and early fraud detection.
Digital lending. Small loans and credit lines approved inside the app are growing, especially for freelancers and small businesses.
Cross-border banking. Holding and converting several currencies in one account is becoming a standard feature, not a premium one.
Digital Banks vs Traditional Banks
| Factor | Digital Banks | Traditional Banks |
|---|---|---|
| Speed | Account opening in minutes | Often days, with paperwork |
| Fees | Lower, often zero-balance | Higher, with minimum balance rules |
| Accessibility | 24/7 app access | Branches plus app |
| Lending | Growing, mostly smaller loans | Wider range, including mortgages |
| Best for | Salary, savings, freelancers, SMEs | Large loans, complex needs, in-person service |
How to Choose the Right Digital Bank in the UAE
Decision Factors
Start with what you need most. Ask yourself:
- Will my salary go into this account?
- Do I want to keep a minimum balance?
- Do I need business features?
- Do I want Islamic banking?
- Do I send or spend money in other currencies often?
Use-Case Recommendations
- Salaried employee: Mashreq Neo or Liv
- Freelancer or small business: Wio Business or NeoBiz
- Islamic banking: ruya
- Corporate or wealth needs: Zand
- Frequent money sender: Compare Wise or e&Money with a bank’s transfer fees
Checklist Before You Open an Account
- Confirm the provider holds a valid licence.
- Read the full fee schedule.
- Check savings conditions, not only the headline rate.
- Look at transfer costs to the countries you use most.
- Test the app’s reviews and customer support options.
- Keep one backup account in case of technical problems.
Conclusion and Next Steps
Digital banking UAE has matured quickly. Clear regulation, instant payments through Aani, and strong competition between neobanks and traditional banks give residents real choices. Digital banking is becoming the default because it is faster, cheaper, and simpler for most everyday needs. Traditional banks still matter for large loans and in-person service, so many people use both.
Your next step is simple. Pick two providers that match your needs, compare their fees, and open the one that fits your daily life. To keep learning, browse our related guides on online banking UAE, payment solutions, and digital finance.
Frequently Asked Questions
What is digital banking in the UAE?
Digital banking in the UAE means managing your account fully through an app, from opening it with your Emirates ID to sending money and getting a card, without visiting a branch.
Is online banking UAE the same as digital banking?
No. Online banking is an app or website added to a traditional bank. Digital banking is built around the app from the start, and some digital banks have no branches.
Are digital banks in the UAE safe?
Yes, when they are licensed by the Central Bank of the UAE. They use encryption, biometric login, and fraud monitoring. You should still protect your OTP and PIN.
Can I open a digital bank account without a salary?
Often yes. Many digital banks offer zero-balance accounts with no salary requirement, although higher savings rates may depend on salary transfer or activity.
What is Aani?
Aani is the UAE’s instant payment platform. It lets you send money between participating banks and apps in about three seconds using a mobile number or alias.
Can tourists open a digital bank account in the UAE?
Usually not, because most providers require a valid Emirates ID. Tourists often use prepaid cards or wallets instead.
Which digital bank is best for freelancers?
Wio Business and NeoBiz are popular choices. The best one depends on your fees, features, and whether you need invoicing or accounting tools.
How long does it take to open a digital bank account in the UAE?
Many apps finish onboarding in minutes. Final approval may take longer if the bank needs extra documents.